Guide To VA Foreclosed Homes For Active Duty Military With No Down Payment
- Understanding Military Mortgage Financing Options
- Finding a Repossessed Property Through an Auction
- Working With an Approved Lender
- Real-World Pricing Insights and Lender Comparisons
Securing a residence while serving on active duty presents distinct financial opportunities through government-backed programs designed for minimal upfr...
Securing a residence while serving on active duty presents distinct financial opportunities through government-backed programs designed for minimal upfront capital. Eligible service members can evaluate distressed real estate opportunities across the country without needing a traditional down payment. Understanding lender terms and property acquisition rules helps ensure sound long-term choices.
Navigating real estate opportunities while serving in the armed forces requires an understanding of distinct government initiatives and specialized lending programs. Active duty personnel often move between duty stations, making standard residential acquisitions complex and financially burdensome. Distressed listings and government-managed inventories present unique opportunities for service members seeking housing stability without expending substantial upfront cash reserves.
Understanding Military Mortgage Financing Options
Qualified personnel have access to home loan benefits backed by the government that remove conventional down payment requirements. When looking to secure military mortgage financing, service members can use these guarantees to acquire residential real estate with zero cash down, provided the house meets core safety and structural criteria. Unlike conventional lending, these specialized programs do not mandate monthly private mortgage insurance, which directly lowers the total ongoing monthly commitment. This structural advantage gives active personnel a reliable method for building equity even during periods of relocation or frequent service reassignments.
Finding a Repossessed Property Through an Auction
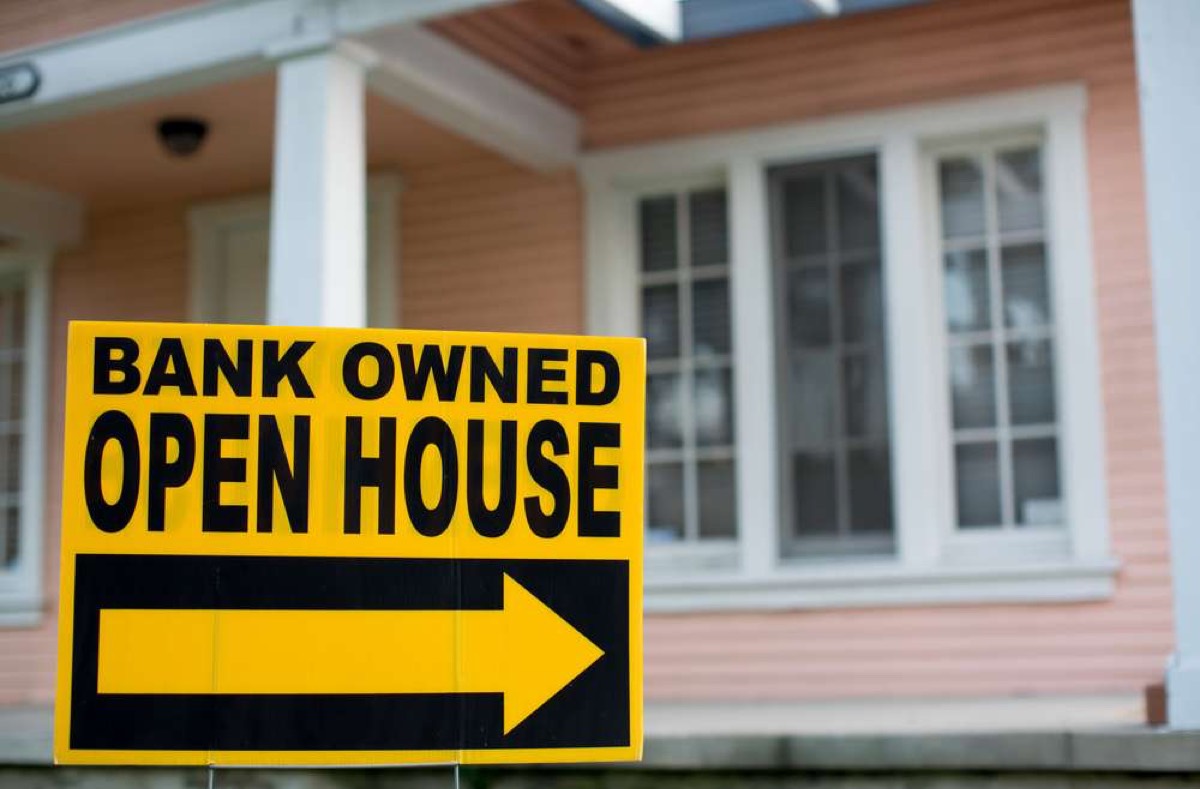
When a loan defaults, the associated residence often enters the market as a repossessed property, sometimes distributed via a regional or digital auction. Purchasing real estate through an auction or distressed sales list can offer discounted purchase valuations, but it also demands thorough due diligence. Some properties sold through public sales channels may require considerable rehabilitation or cash purchases that standard loans cannot cover. However, government portfolios occasionally include homes that have already passed initial safety inspections, permitting qualified service members to utilize standard guarantee benefits to acquire them without significant financial friction.
Working With an Approved Lender
Identifying an experienced lender remains essential when pursuing homes acquired through default proceedings. Not every financial institution specializes in military lending rules or understands how to process loans for homes acquired out of default portfolios. A qualified lender can quickly establish certificate of eligibility status, verify base allowance for housing figures, and coordinate the specific property appraisal required by federal guidelines. Establishing this relationship early in the house hunting process provides clear boundaries regarding purchasing limits and closing cost expectations.
Real-World Pricing Insights and Lender Comparisons
Acquiring real estate with no money down does not completely eliminate initial or ongoing expenses. Buyers must consider funding fees, local escrow reserves, appraisal fees, and potential property repairs. The mandatory funding fee can often be rolled directly into the loan balance, reducing immediate out-of-pocket strain. Furthermore, interest rates fluctuate based on market movements, individual credit profiles, and loan terms, meaning that advertised rates should always be treated as general estimates.
To better understand the financial landscape, comparing terms among established institutions helps identify competitive lending packages for service personnel.
Prices, rates, or cost estimates mentioned in this article are based on the latest available information but may change over time. Independent research is advised before making financial decisions.
Building Long-Term Ownership and Value
Achieving lasting ownership requires careful analysis of property condition and long-term resale viability. Homes previously vacated due to financial distress might have deferred maintenance issues, ranging from aged plumbing fixtures to worn roofing materials. Conducting a thorough private inspection alongside the mandatory federal appraisal protects the buyer from unexpected capital expenditures. Over time, responsible management and steady amortization allow military households to convert a distressed acquisition into a valuable wealth-building asset that can later serve as a rental property or primary family home.
Special Considerations for the Veteran Community
Transitioning from active service to civilian life often alters household budgeting, which makes early property choices vital. Both active service personnel and any veteran considering distressed market entries should evaluate property taxes, neighborhood amenities, and local economic resilience. Ensuring the asset matches long-term personal goals ensures that zero-down financing functions as an empowering financial foundation rather than a financial strain.
Careful planning, diligent lender selection, and realistic budgeting allow military buyers to successfully navigate the distressed housing market and establish secure residential equity.
Please note: This guide is general information, not professional advice. Prices, eligibility rules and program details change, so confirm with the provider or a qualified professional before you act.